Why Marina gives some developers incentives
These projects are not part of the UUT proposal. They are included because they show how Marina has used development agreements, tax-sharing, fee deferrals, infrastructure obligations and performance-based incentives to expand the tax base, create housing and jobs, and obtain public improvements. Each use case should be judged on its own documented exchange.
Eight development examples
| Use case | Type | High-level City / developer arrangement | Expected City return / ROI logic |
|---|---|---|---|
| The Dunes master development | Mixed-use master plan | Long-term development rights paired with affordable housing, infrastructure, parks and commercial/hotel obligations. | Large new residential/commercial tax base; documented Dunes Park contribution raised to $8.47M; retail, lodging and jobs. |
| SpringHill Suites / initial Dunes hotel incentive | Hotel / TOT-generating use | Impact-fee deferral and an originally structured 50/50 use of new TOT to repay deferred fees; deadlines and repayment obligations applied when schedule slipped. | Hotel rooms and ongoing TOT; incentive was tied to actually opening and producing new money raised. |
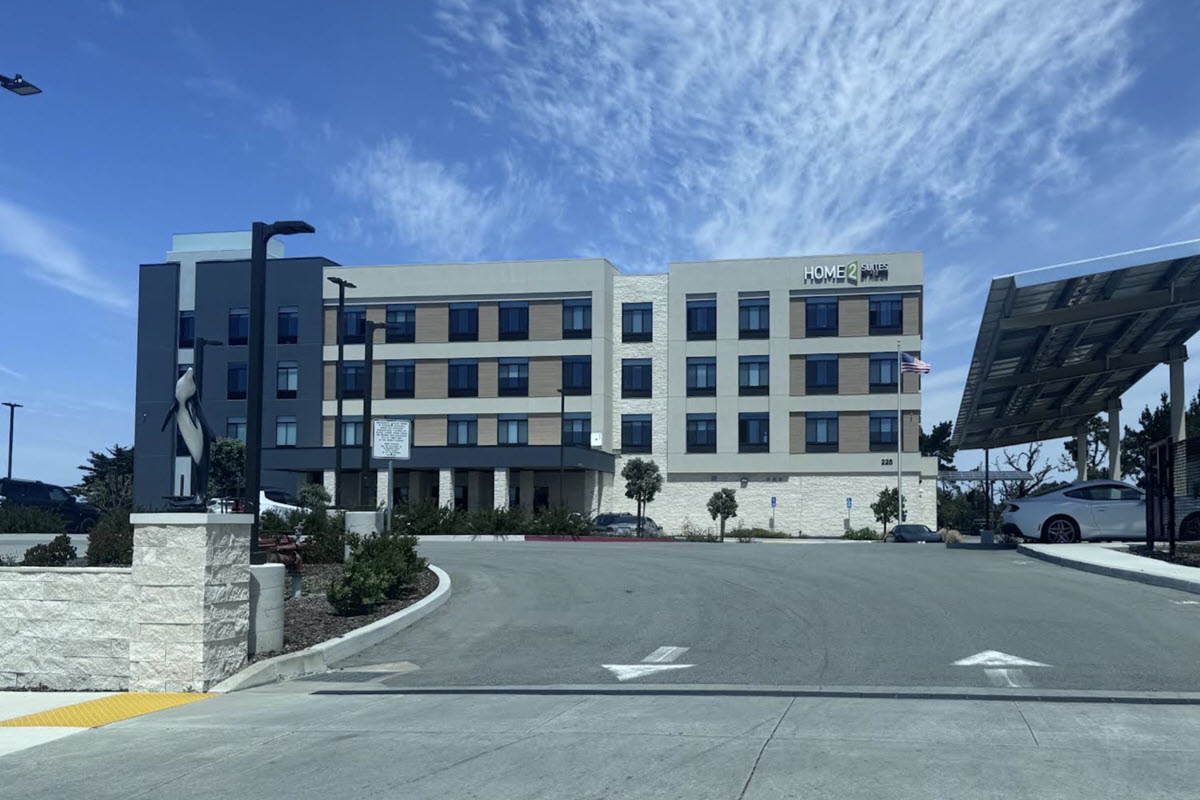
| Hampton Inn | Hotel / private development | No special City economic-development subsidy was located in the City records reviewed for this site. | Illustrates that not every hotel requires a special subsidy; benefit is lodging supply, TOT and employment. |
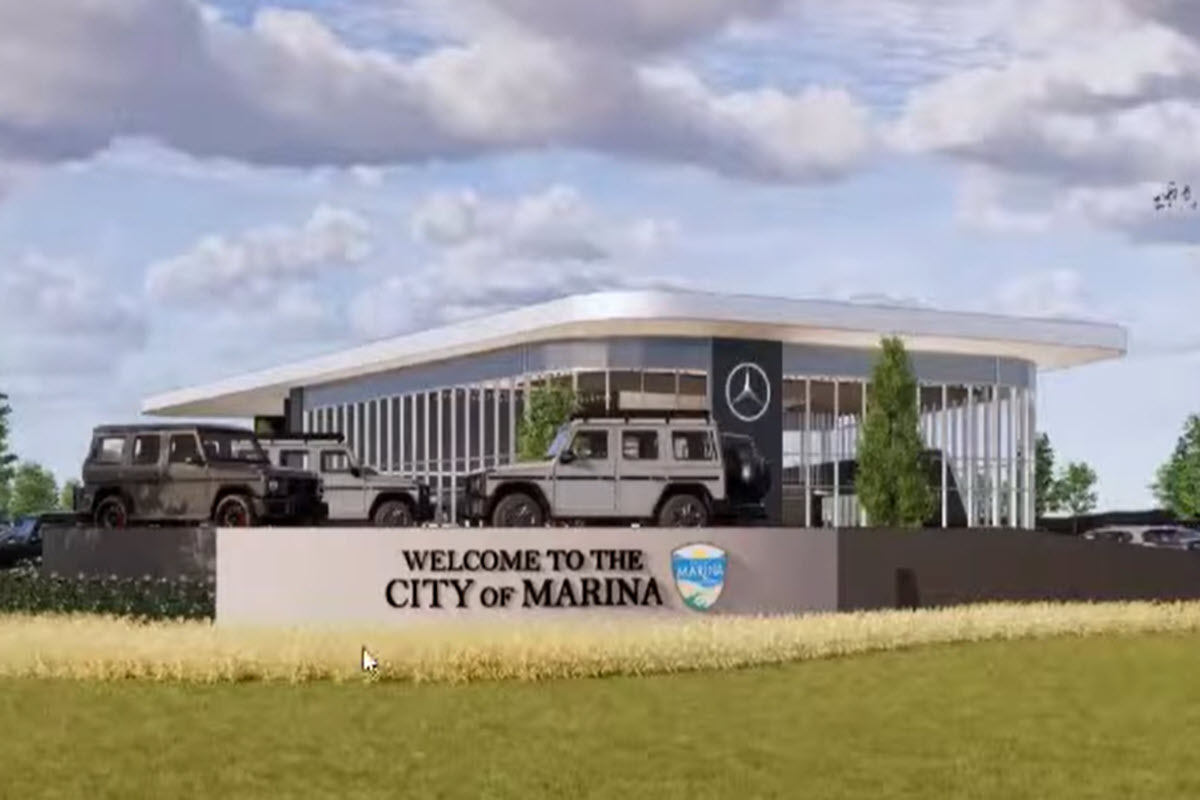
| Mercedes-Benz of Monterey at The Dunes | Auto retail / sales-tax sharing | Temporary sharing of part of the City's local sales-tax increment to overcome high site-development costs. | City model: $11.635M direct new tax over seven years while incentive cap was analyzed at $5M; after sharing ends, full local share remains with City. |
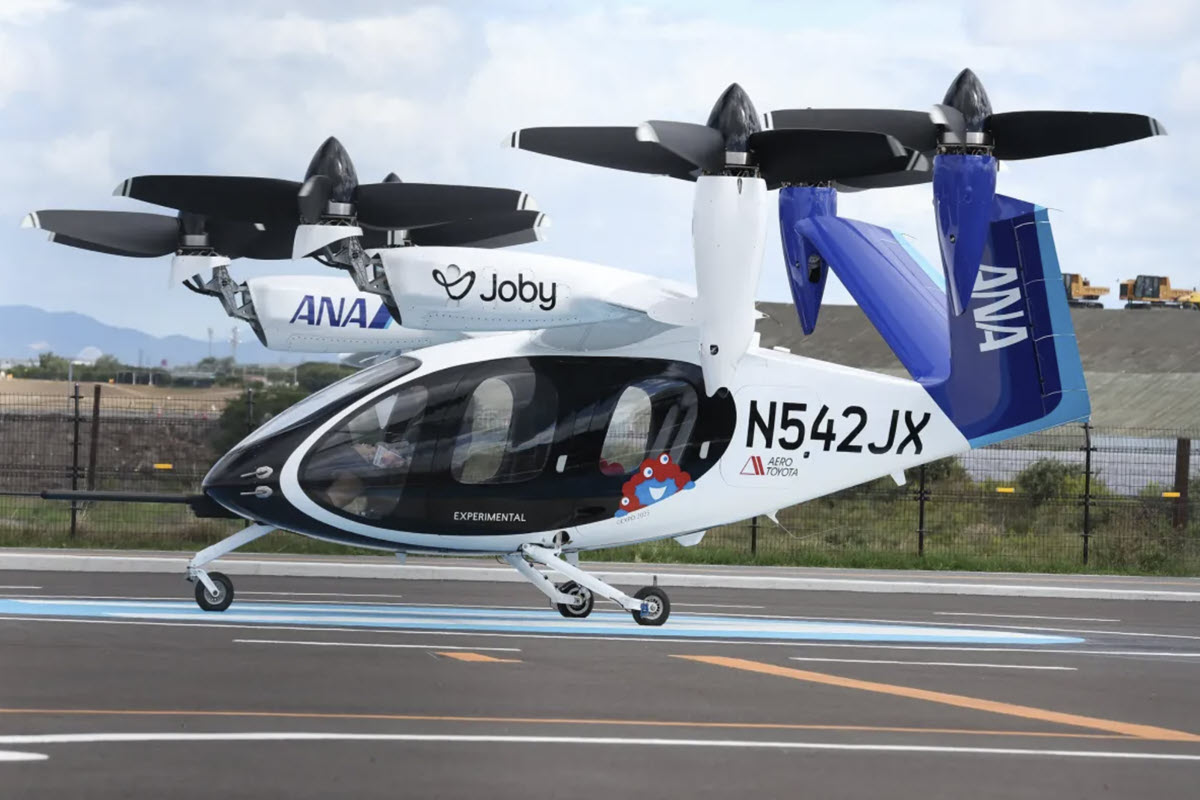
| Joby Aviation | Advanced manufacturing / airport tenant | Performance-based property-tax sharing under California's CIIP after minimum investment thresholds. | City estimated ≈$4M property-tax money raised over 15 years plus jobs/economic output; City receives full share after incentive term. |
| New Dunes upper-upscale luxury hotel | Proposed resort / TOT sharing | Proposal to replace three approved midscale hotels with one 150-key upper-upscale resort; preliminary 50:50 TOT sharing of about $25M under study. | Estimated total TOT ≈$2.897M in 2030, $3.702M in 2031 and $3.986M in 2032; City would retain a share while assistance is active. Not yet a final deal. |
| Sea Haven | Residential master plan | ≈1,050 homes with BMR obligations and development agreement; park obligations and fees modified as inflation and project conditions changed. | Housing supply, affordable ownership, property-tax and fee growth; 18-acre park ultimately funded through developer obligations/fees and City action. |
| Marina Station | Mixed-use master plan / special tax district | More than 1,300 homes plus retail, office and industrial/flex; special tax district special taxes and bonds fund development-related facilities/services. | Growth finances a proportionate share of its infrastructure while adding long-term property, sales/business and employment base. |
How Marina's development tools changed over time
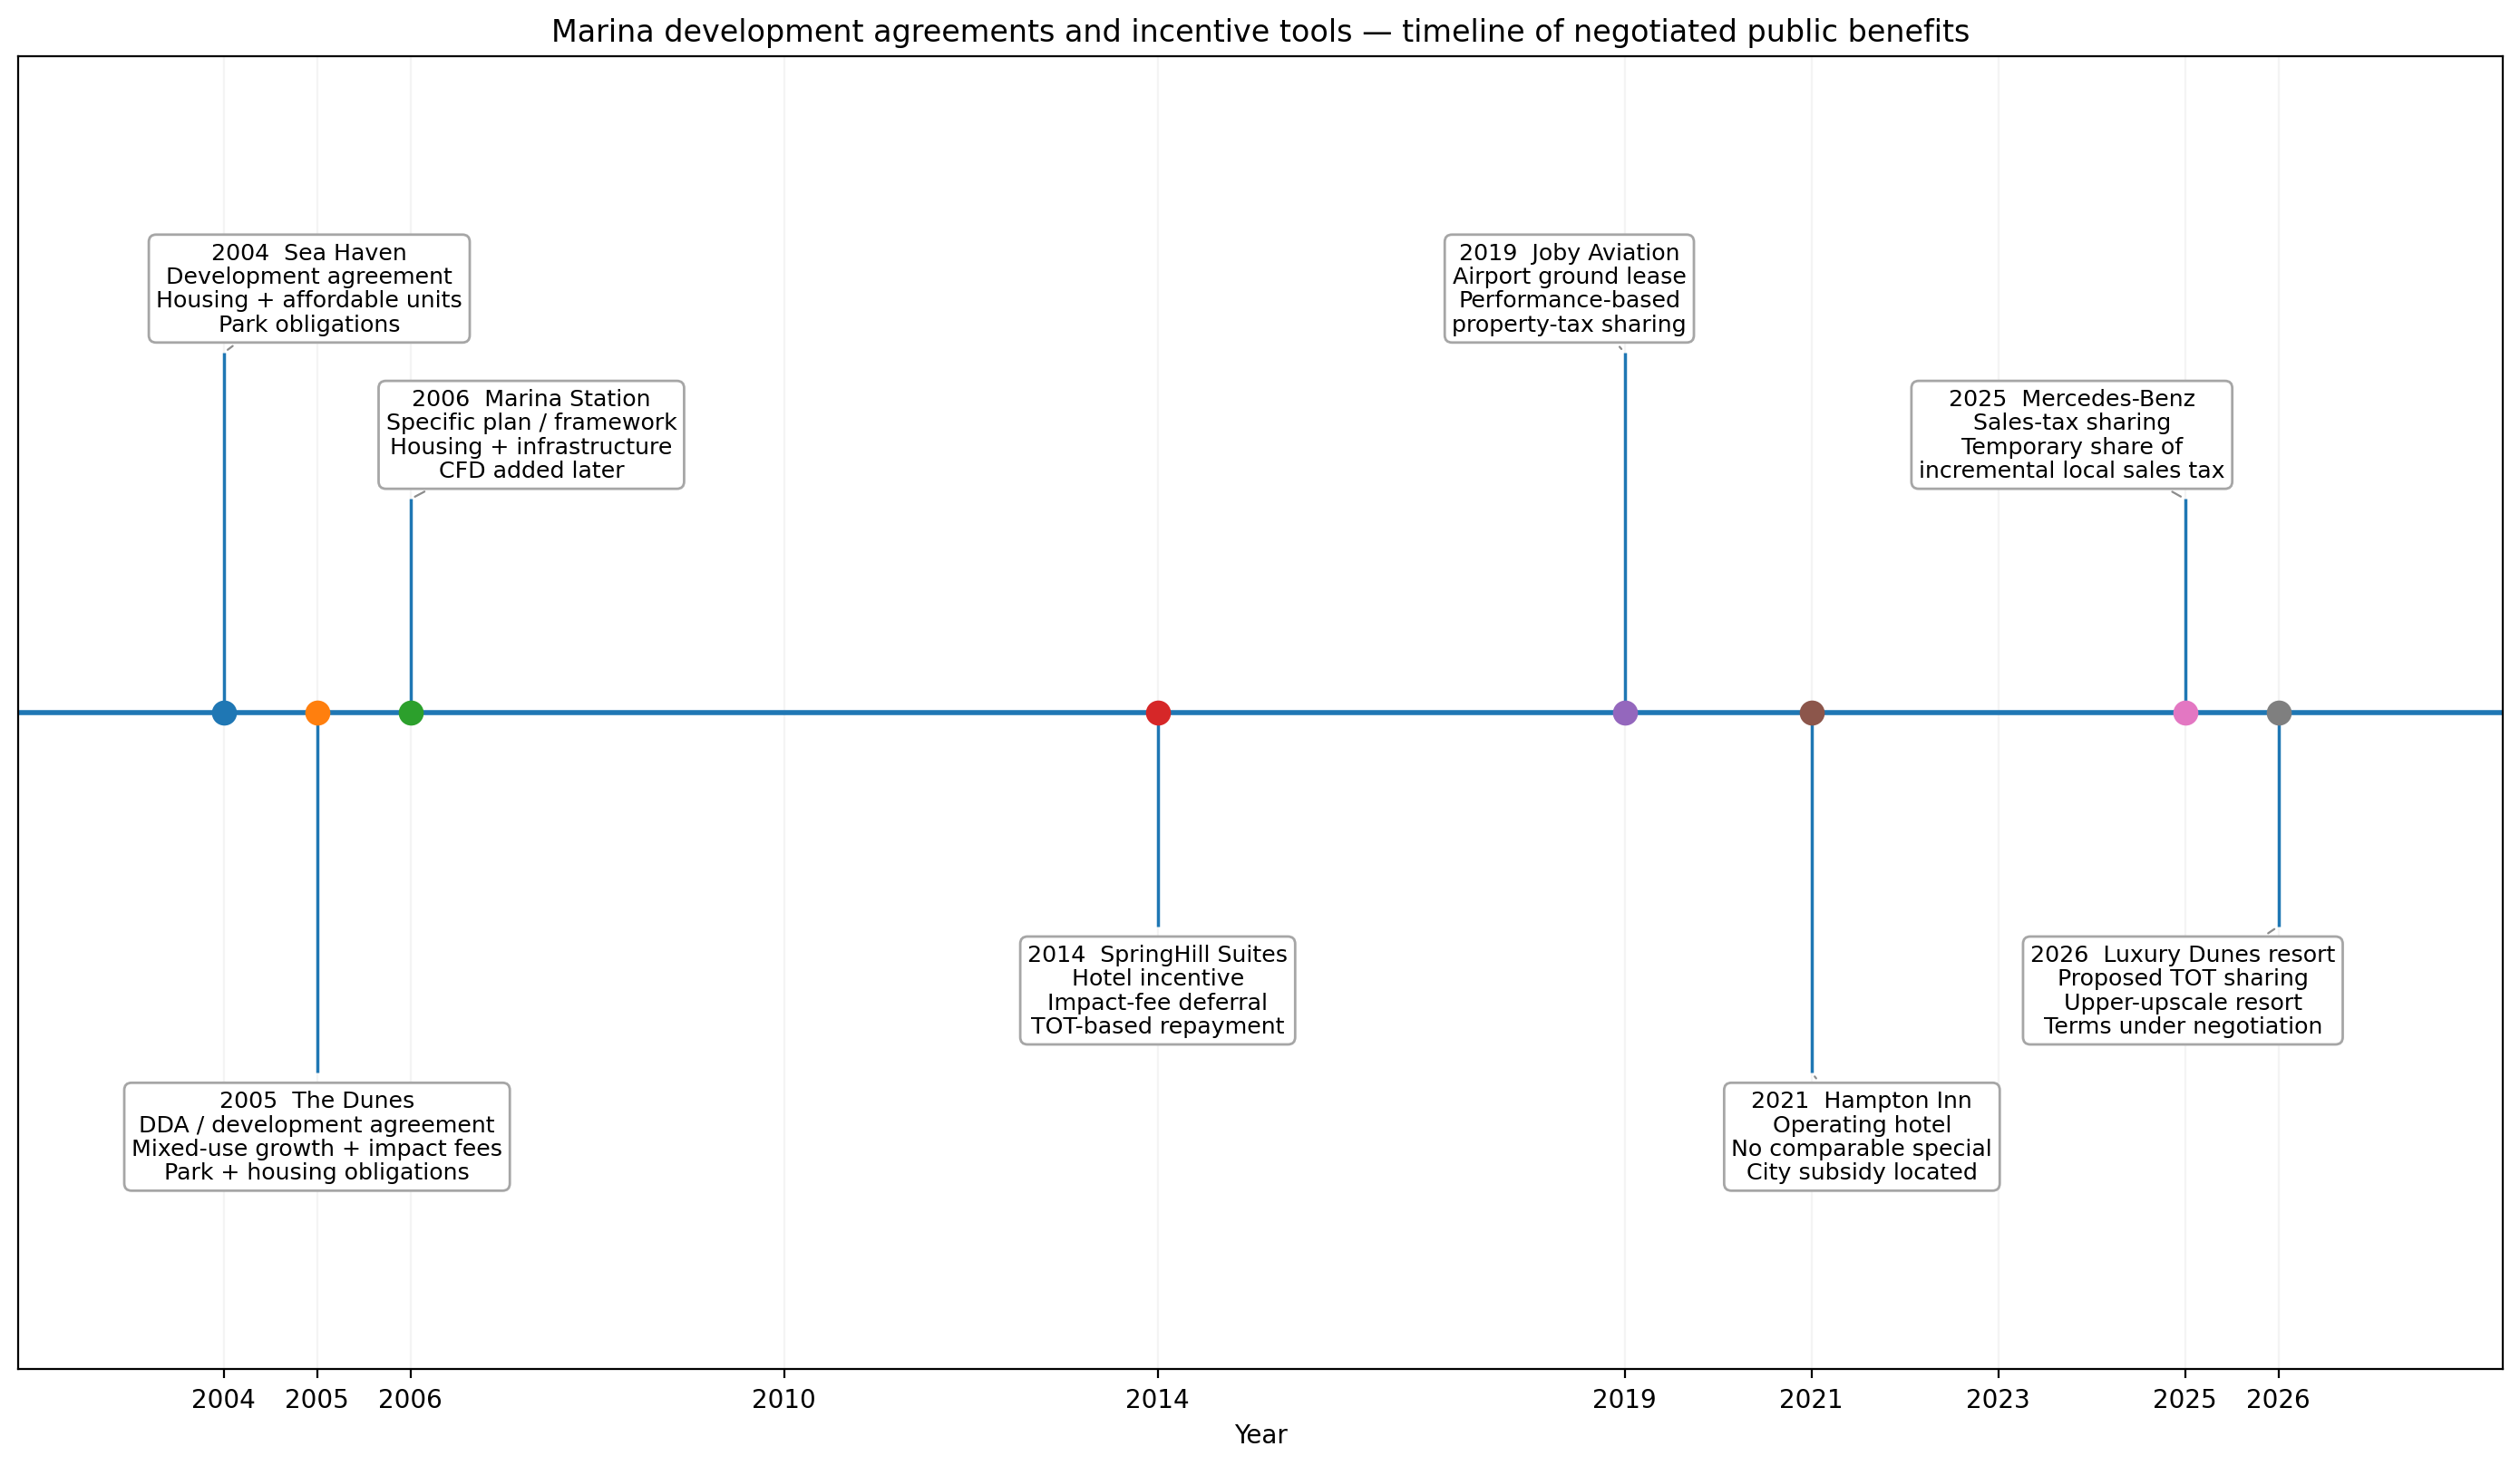
Marina has not used one standard form of developer assistance. The timeline shows the principal mechanism attached to each use case: development agreements and impact-fee obligations for the large master plans, a fee deferral for SpringHill, performance-based property-tax sharing for Joby, temporary sales-tax sharing for Mercedes, and proposed TOT sharing for the new luxury hotel.
| Development | Initial milestone | Principal negotiated benefit mechanism | Public return sought |
|---|---|---|---|
| Sea Haven / Marina Heights | 2004 development agreement | Development rights paired with affordable-housing schedule, fees and park obligations. | 1,050 homes, affordable housing, infrastructure, impact fees and public park/open-space improvements. |
| The Dunes | 2005 entitlements / DDA and DA | Master-plan development rights, impact fees, affordable-housing triggers, park contributions and commercial/hotel obligations. | Housing, retail, hotel/TOT, sales tax, jobs, infrastructure and public amenities. |
| Marina Station | 2006 master-plan approval | Large mixed-use development framework; later special tax district special taxes/bonds for facilities and services. | Growth intended to finance a proportionate share of its own infrastructure and service burden. |
| SpringHill Suites | 2014-era incentive / 2017 opening | Impact-fee deferral with TOT-linked repayment and deadlines. | Get the hotel built sooner, create rooms/jobs/TOT, and repay the deferred obligation. |
| Joby Aviation | 2019 ground lease / 2023 CIIP | Performance-based sharing of incremental property tax after eligible project investment. | Advanced-manufacturing investment, airport activity, jobs and long-term property-tax growth. |
| Hampton Inn | Operating by 2021 | No comparable special City subsidy located in the reviewed City record. | Normal hotel benefits: lodging, jobs and TOT without an identified special tax-sharing deal. |
| Mercedes-Benz | 2025 agreement / 2026 amendment | Temporary sharing of incremental local sales-tax money raised. | Overcome site-development cost, secure a $40M+ investment and add a major recurring sales-tax source. |
| Upper-upscale Dunes resort | 2026 proposal | Proposed 50:50 sharing of new hotel TOT, subject to final cap/term/performance conditions. | Replace stalled midscale hotel concepts with a higher-money raised resort and larger visitor-spending/TOT base. |
What could these deals return to the City?
This section does not pretend every development has a published municipal ROI study. Where Marina published a financial estimate, the site projects that documented number forward under deliberately simple assumptions. Where the City did not publish a defensible project-specific money raised stream, the page says so instead of inventing one.
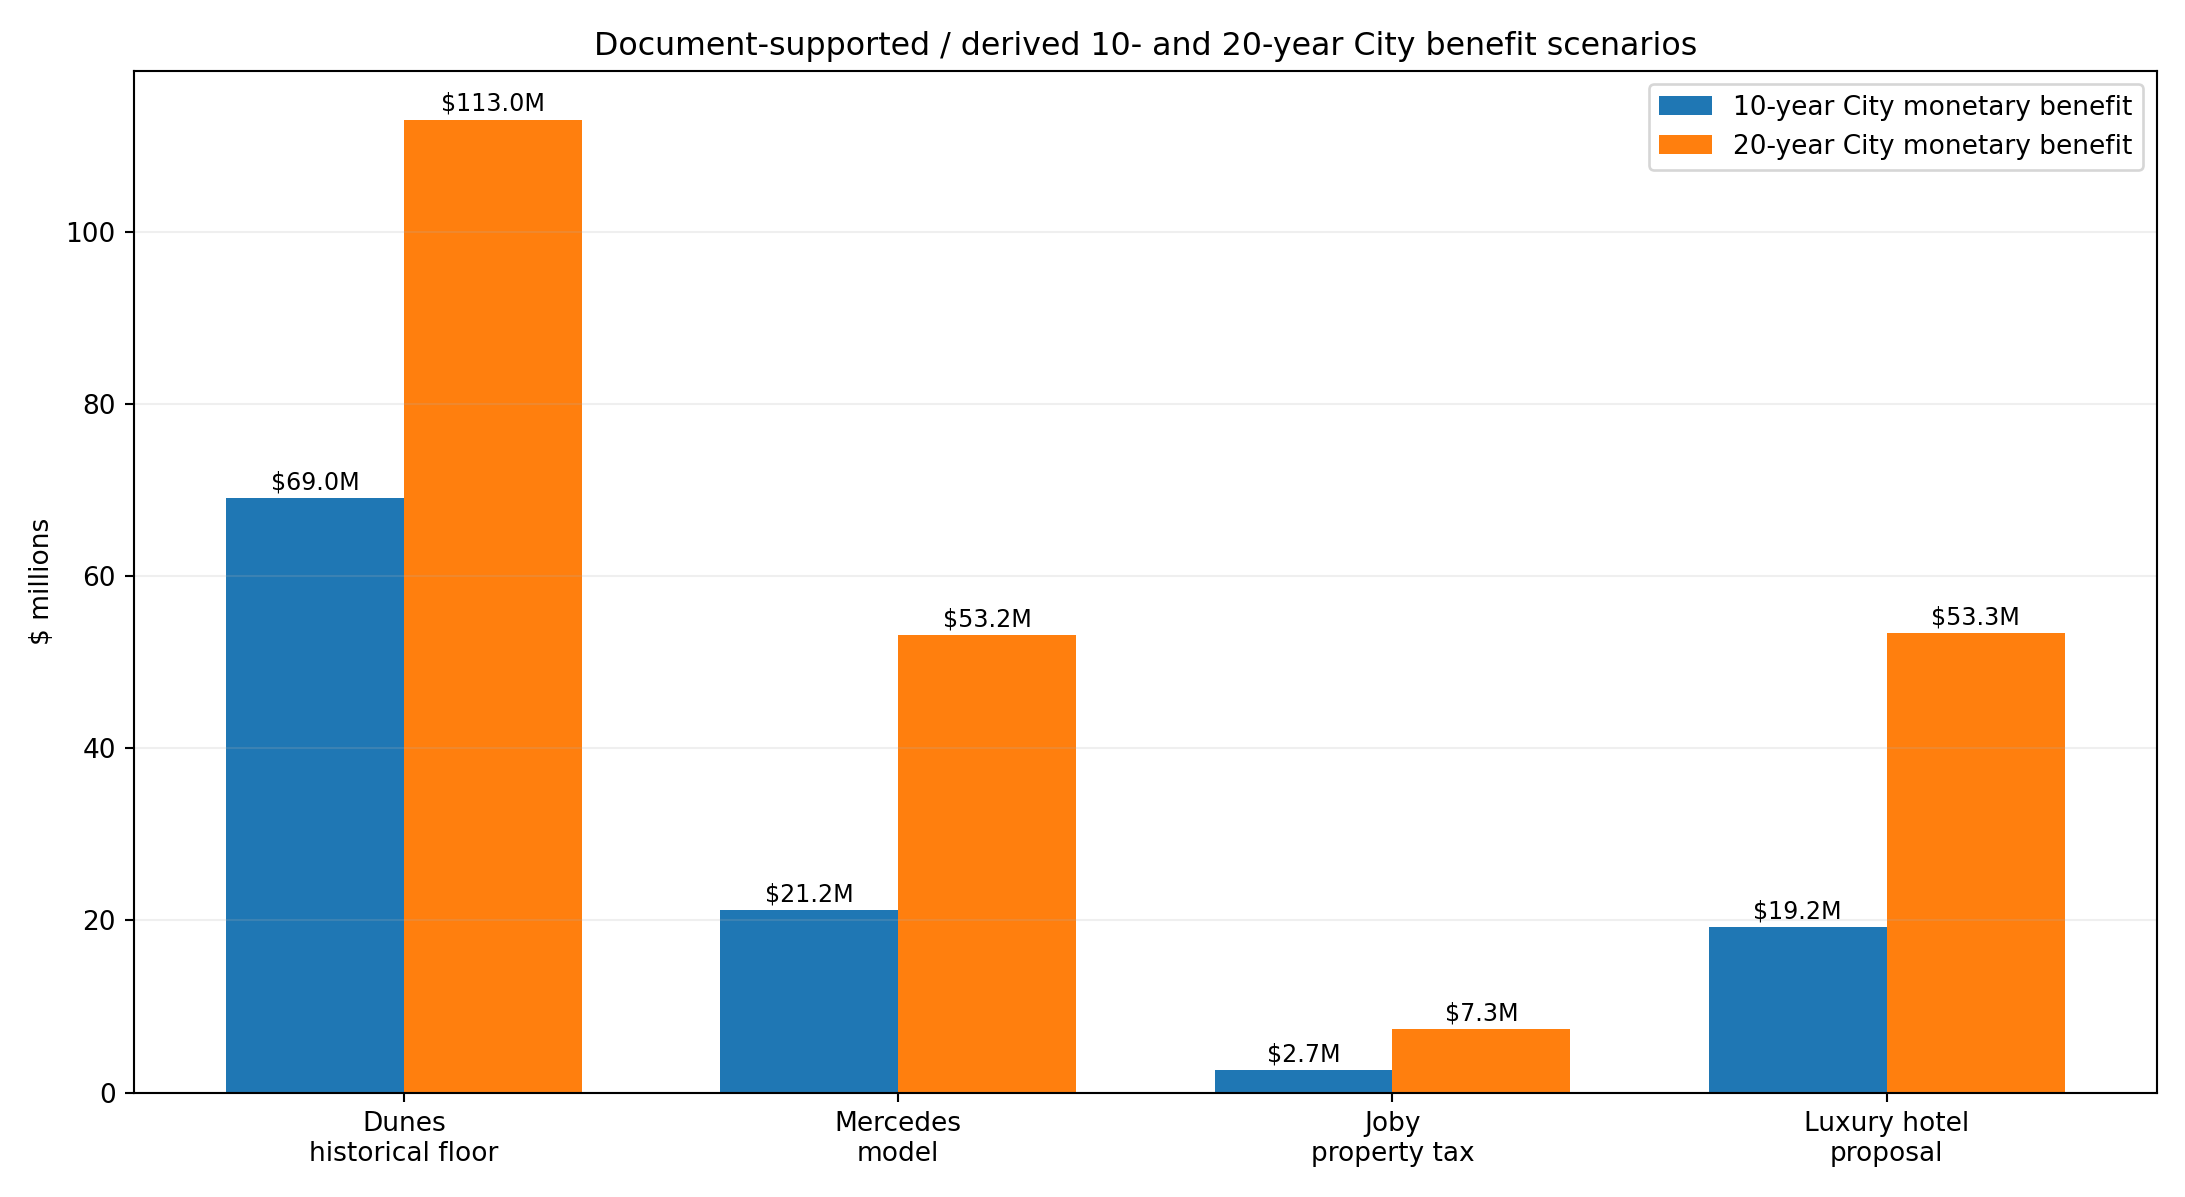
| Project | 10-year City monetary perspective | 20-year City monetary perspective | Growth perspective | 2026 fulfillment status |
|---|---|---|---|---|
| The Dunes | Using only the City's 2019 documented $4.4M/year sales-tax + TOT base and >$25M one-time impact fees: ≥$69.0M. | Same historical floor held flat: ≥$113.0M. | Up to 1,237 homes, affordable/workforce housing, retail, lodging, parks and additional commercial phases. | Advanced but incomplete. Phase 2 North infrastructure/commercial and later residential work continued in 2026. |
| SpringHill Suites | No hotel-specific City money raised series was found that supports a defensible 10/20-year estimate. The hotel is part of the Dunes money raised base above. | 106-room hotel added lodging inventory and recurring TOT. | Operating since 2017; original fee-deferral/repayment issues were subsequently addressed. | |
| Hampton Inn | No project-specific subsidy or City money raised forecast located; do not manufacture an ROI. | Operating hotel adds rooms, employment and 14% Marina TOT. | Operating by 2021; 2024 City records treat it as an existing facility. | |
| Mercedes-Benz | City model + flat post-sharing money raised: ≈$21.22M direct City tax. | Same conservative flat assumption: ≈$53.17M. | $40M+ investment; 80+ initial jobs, potentially 140+; significant sales-tax base. | Agreement amended Apr. 2026; land acquired; design/CEQA processing continued in June. Budget anticipated operation late FY2026-27. |
| Joby Aviation | Linearized City property-tax estimate: ≈$2.67M. Separate economic-impact model: ≈$3.0B local economic output if $300M/year is sustained. | Derived property-tax estimate: ≈$7.33M; ≈$6.0B economic output if the City's annual estimate holds. | Large advanced-manufacturing employment and airport investment; incentive requires eligible project investment. | Joby remains an active airport tenant; City approved an additional ground lease in Apr. 2026. The full 580,000-sq-ft/$700M expansion assumptions remain performance estimates, not completed facts. |
| Upper-upscale Dunes resort | If preliminary 50:50 TOT sharing is adopted and 2032 TOT stabilizes near $3.986M: City retains ≈$19.24M over first ten day-to-day years. | Assuming developer share caps at ≈$25M and then full TOT returns to City: ≈$53.35M. | 150 keys, villas, restaurant/spa/events, potential 200–300 jobs and higher-value visitor market. | Proposal only. July 2026 Council directed additional development-agreement and subsidy work; no final subsidy terms yet. |
| Sea Haven | No public project-specific 10/20-year General Fund money raised forecast was found. Monetary benefits include impact/permit fees and property-tax growth, but the development agreement changes make a simple ROI number unreliable. | 1,050 homes, 210 affordable, 35 acres parks/open space; buildout targeted around 2030. | Advanced buildout; BMR sales active; 18-acre park broke ground July 2026 after City assumed construction responsibility. | |
| Marina Station | No defensible public 10/20-year City money raised total found. The stronger financial protection is structural: the special tax district is expressly intended to keep the project financially neutral or better. | 1,360 homes; 60,000 sq ft retail; 143,808 sq ft office; 651,624 sq ft business/industrial; 20% affordable housing. | Early phases / infrastructure. special tax district formed and special-tax/bond election certified Mar. 2026; buildout estimated through roughly 2036. | |
Were these bad deals for residents?
| Project | Assessment from the current record | Main resident protection | Main open risk |
|---|---|---|---|
| Dunes | Evidence does not support calling the overall agreement a bad deal. By 2019 completed development was already producing ≈$4.4M/year in sales tax/TOT and >$25M in one-time impact fees. | Affordable-housing triggers, impact fees, special tax districts, park contribution, permit-stop remedies. | Repeated amendments, long delivery horizon, hotel/park timing and reduced/changed obligations deserve continued scrutiny. |
| SpringHill | Mixed execution, not evidence of a giveaway. The hotel opened after delay; fee deferral was tied to repayment/TOT mechanics. | Repayment obligations and deadlines. | Delay shifted timing risk to City and complicated enforcement. |
| Hampton | No basis found for a “subsidy giveaway” characterization. | No comparable special City subsidy located. | Normal hotel land-use/environmental/service impacts. |
| Mercedes | Financial case is favorable if the dealership opens and sales targets are achieved; benefit is not yet realized. | Temporary sharing of incremental money raised; City keeps money raised during sharing and 100% after term. | Construction/market risk; project is not day-to-day yet. |
| Joby | Structure strongly protects the City relative to an upfront subsidy. | CIIP requires at least $150M eligible investment before incentive payments; incentive applies to incremental taxes. | Scale of future investment/jobs may be lower or later than estimated. |
| Luxury resort | Too early to call good or bad; this is the deal requiring the most current scrutiny. | City can negotiate cap, term, performance milestones and default remedies before approval. | ≈$25M proposed TOT sharing is large; luxury demand, construction cost and opening schedule remain uncertain. |
| Sea Haven | Mixed outcome with a legitimate resident concern. Housing/affordable units are real, but the City ultimately assumed park-construction responsibility as costs rose. | Developer still pays adjusted park fee; affordable-housing and deed-restriction obligations remain. | City carries construction-cost/delivery risk for park; amendments can make original obligations harder for residents to follow. |
| Marina Station | Too early for outcome judgment, but financial-neutrality structure is resident-protective. | special tax district funds project-area maintenance and half of City cost to operate/maintain a fire station serving project/general community. | Large, long buildout; special-tax burden is borne by future property owners and assumptions must remain sufficient over time. |
The strongest evidence-based conclusion is therefore not that Marina has systematically ignored residents in favor of developers. The record shows substantial public concessions in some cases, but also impact fees, affordable housing, special tax districts, performance triggers, tax-sharing caps, park/infrastructure contributions and financial-neutrality requirements. The legitimate criticism is narrower: the complexity and repeated amendments make it difficult for residents to see the total bargain without doing exactly this kind of reconstruction.
What people say versus what records show
Public discussion is part of the evidence landscape, but it is not interchangeable with a development agreement, budget or financial study. The examples below use resident and elected-official comments to identify the questions people are asking, then test the actual factual proposition against primary records.
a local Marina activist: “profit,” tax sharing and developer contributions
Public Facebook search results show a local Marina activist repeatedly raising questions about whether Marina receives “profit” from The Dunes, describing the July 2026 hotel discussion as “profit sharing with developers,” and citing an approximately $8.6M developer contribution in another Marina development discussion. Facebook would not reliably expose the complete post bodies during this research pass, so the site assesses only statements visible in indexed search results and does not attribute additional claims to him.
| Public statement / framing | Accuracy against the record | More precise wording |
|---|---|---|
| “Does the City receive any profit from The Dunes?” | The question is fair, but “profit” is the wrong accounting test. Marina is not an equity partner entitled to developer profit. It receives taxes, fees, land/infrastructure/contributions and economic activity. By 2019 the City documented ≈$4.4M/year sales tax + TOT and >$25M in one-time impact fees from development already completed. | Ask: “What net financial benefit does the City receive after service and infrastructure obligations?” |
| July luxury-hotel discussion described as “profit sharing with developers.” | Imprecise. The proposal is primarily Transient Occupancy Tax money raised sharing, not a share of developer day-to-day profit. The City would temporarily share tax money raised generated by the hotel to help finance construction. | “Proposed sharing of new hotel TOT, subject to a cap/term.” |
| Developer contributes about $8.6M. | Substantially consistent if referring to the Dunes Park package. The documented amount is $8.47M: $4.67M inflation-adjusted base contribution + $3.8M additional contribution tied to affordable housing. | Use $8.47M and identify the trigger/source. |
Public comments are not the same as City records
This register is intentionally neutral. A person's inclusion does not mean this site endorses the statement or treats a social-media post as proof. Current candidates are identified because election-period comments deserve additional context. As of August 12, 2026, the City's official Candidate Watch lists Mike Moeller and Liesbeth Visscher as qualified mayoral candidates and Brian McCarthy as a qualified District 1 candidate.
| Person | Public role / context | Located public perspective | How this site treats it |
|---|---|---|---|
| Grace Silva-Santella | Former CFCAC participant / resident commenter | Has publicly questioned the final UUT structure and, in a user-supplied Nextdoor screenshot, said the committee's “up to 7%” recommendation was later interpreted more broadly than she intended. Indexed Facebook posts also show her raising City Hall siting and UUT concerns. | Useful first-person evidence about how one committee member understood the process; not a substitute for the formal CFCAC vote or report. |
| Bruce Delgado | Mayor through 2026 | Official records show he participated in the Council decisions that moved the 2026 UUT forward. Publicly indexed material also records that he had favored a smaller $20M bond approach during the earlier Measure U debate. | Use Council votes, minutes and City records as the primary evidence; social posts only for context. |
| Brian McCarthy | District 1 Councilmember; qualified 2026 District 1 candidate | Publicly indexed Facebook comments state that he voiced strong dissent regarding the actual UUT structure, while he had publicly supported the 2024 Measure U police/fire bond campaign. | Shows that support for replacing facilities does not necessarily equal support for the final UUT design. Candidate status is disclosed. |
| Liesbeth Visscher | Mayor Pro Tem; qualified 2026 mayoral candidate | Indexed posts show her calling for UUT money raised modeling to be explained clearly to residents and participating in the Council's facilities/UUT process. | Use official votes/minutes for policy positions; candidate-related social media is contextual and labeled. |
| Mike Moeller | Resident commenter; qualified 2026 mayoral candidate | Indexed Marina-group posts show him engaging directly on the proposed UUT, facilities budget and committee process, including thanking committee members while questioning how the tax and facilities plan were being developed. | Candidate context is disclosed. Only complete, retrievable statements should be quoted; snippets are treated as pointers rather than proof. |
| Elisabeth Billingsley | Longtime Marina civic participant | Searches located extensive public civic participation, including water-policy advocacy, but did not locate a sufficiently complete development/UUT statement that could be summarized reliably for this page. | Listed in the research register; no position is inferred from unrelated civic activity. |
| Paul Manuel | Marina resident / public commenter | Public records and social indexing confirm participation in Marina civic discussions, but this research pass did not locate a complete development/UUT statement reliable enough to characterize. | No political or development position is inferred. |
| Glenn Woodson | Marina resident / public commenter | Indexed public posts include Marina population/growth and General Plan analysis and comments on local infrastructure/public-safety issues. | Resident analysis can identify useful questions or datasets, but City records remain the source of record for factual conclusions. |
Hotel incentives and Measure Q use different money
The proposed upper-upscale Dunes resort and the UUT can fairly be discussed together when asking a broad policy question: Should Marina share future hotel-tax money raised with a private project while asking residents for a new general tax? But the two funding streams should not be combined as though they are the same pot of money.
The hotel proposal contemplates sharing a portion of future Transient Occupancy Tax generated by the new hotel. The approximately $25 million figure is a proposed incentive over time, not a $25 million check drawn today from the facilities budget. The relevant evaluation is the net result: how much new TOT would exist without the project, how much would be shared, how much the City retains during the sharing period, when the sharing ends, and what performance protections are in the final agreement.
The UUT is different. It is a general tax on specified utility services. Whether the hotel incentive demonstrates good or poor financial judgment is a legitimate oversight consideration for a voter, but the hotel agreement does not by itself establish whether the facilities funding gap or UUT money raised calculation is correct.
Bottom line
The development record does not support a simple “developers win, residents lose” narrative, nor does it justify treating every incentive as automatically successful. The Dunes has already produced substantial measurable City money raised; Mercedes and Joby have performance-based structures with potentially large upside but still carry execution risk; Sea Haven demonstrates how inflation can shift project risk back to the City; Marina Station uses a special tax district specifically to avoid burdening the General Fund; and the proposed luxury hotel remains the largest unresolved subsidy decision.
The correct resident question is therefore not “Did a developer get something?” It is: What did Marina give, what did Marina receive, what risks did it retain, and has the developer actually delivered the obligations that justified the concession?
Use case 1 - The Dunes: a long-term mixed-use bargain
The Dunes is not a single subsidy. It is a master development agreement covering residential, retail, hotels, affordable housing, parks and backbone infrastructure on former Fort Ord land. By 2025, City records described substantial portions as built or under construction, including the Dunes Shopping Center, restaurants, Trader Joe's, mixed-use housing, below-market-rate housing, SpringHill Suites and Home2 Suites.
Why the Dunes agreement can benefit Marina
The public record shows more than a developer subsidy. The agreement helped convert former Fort Ord land into housing, affordable and workforce units, retail, hotels, parks, roads, utilities, and a continuing tax base. By 2019, completed development was producing about $4.4 million a year in sales tax and hotel tax, plus more than $25 million in one-time impact fees. The Dunes Park contribution framework was also raised to $8.47 million.
That does not make every amendment or incentive automatically favorable. Delivery delays, changed obligations, and the proposed hotel tax-sharing agreement still deserve review. The documented benefits do show why the overall program should not be described only as money given to Shea or Centex.
A useful example of the negotiated exchange is Dunes Park. In 2019 Marina Community Partners' park contribution was increased for inflation to $4.67M, and the developer agreed to an additional $3.8M contribution triggered by construction of 140 affordable rental units - a total documented contribution of $8.47M. The City took responsibility for design and construction of the park.
ROI/benefit logic: Marina granted long-term development certainty and amendments as market conditions changed; in return the City receives infrastructure, affordable housing, park funding, sales/property/TOT base and economic activity. No single comprehensive “ROI percentage” is published for the entire master plan, so the site does not manufacture one.
2019 Dunes day-to-day/development agreement material ↗ · 2025 Dunes status / traffic update ↗
Use case 2 - SpringHill Suites: incentive with deadlines and repayment
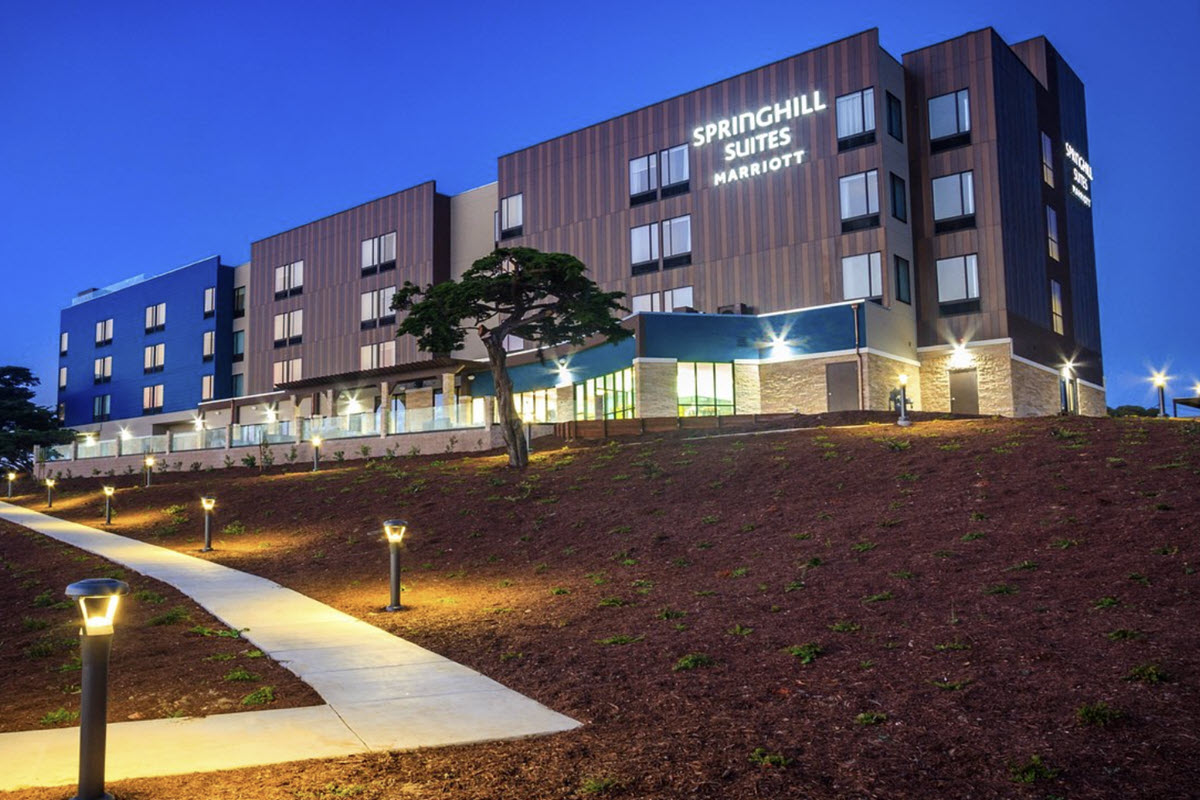
The original SpringHill Suites arrangement is a useful example because it was not an unconditional giveaway. City minutes describe an original impact-fee deferral of roughly $635,000 and a structure in which new hotel Transient Occupancy Tax (TOT) would be split so that part remained in the General Fund and part repaid the deferred fee obligation. The developer also had construction/opening deadlines.
The hotel missed the original schedule and ultimately opened in June 2017. Later Council discussions addressed repayment of the impact-fee obligation and a separate $100,000 extension-related amount. In 2018 the developer asked to revisit the repayment and requested a similar incentive for a future hotel.
ROI/benefit logic: the incentive was intended to bridge funding so a hotel would open and create a recurring TOT stream. The City's protections were timing requirements and repayment obligations. The record shows that when the schedule was missed, the incentive did not simply disappear into a permanent subsidy.
April 17, 2018 SpringHill incentive/repayment discussion ↗ · July 17, 2018 follow-up ↗
Use case 3 - Hampton Inn: development without a located special subsidy
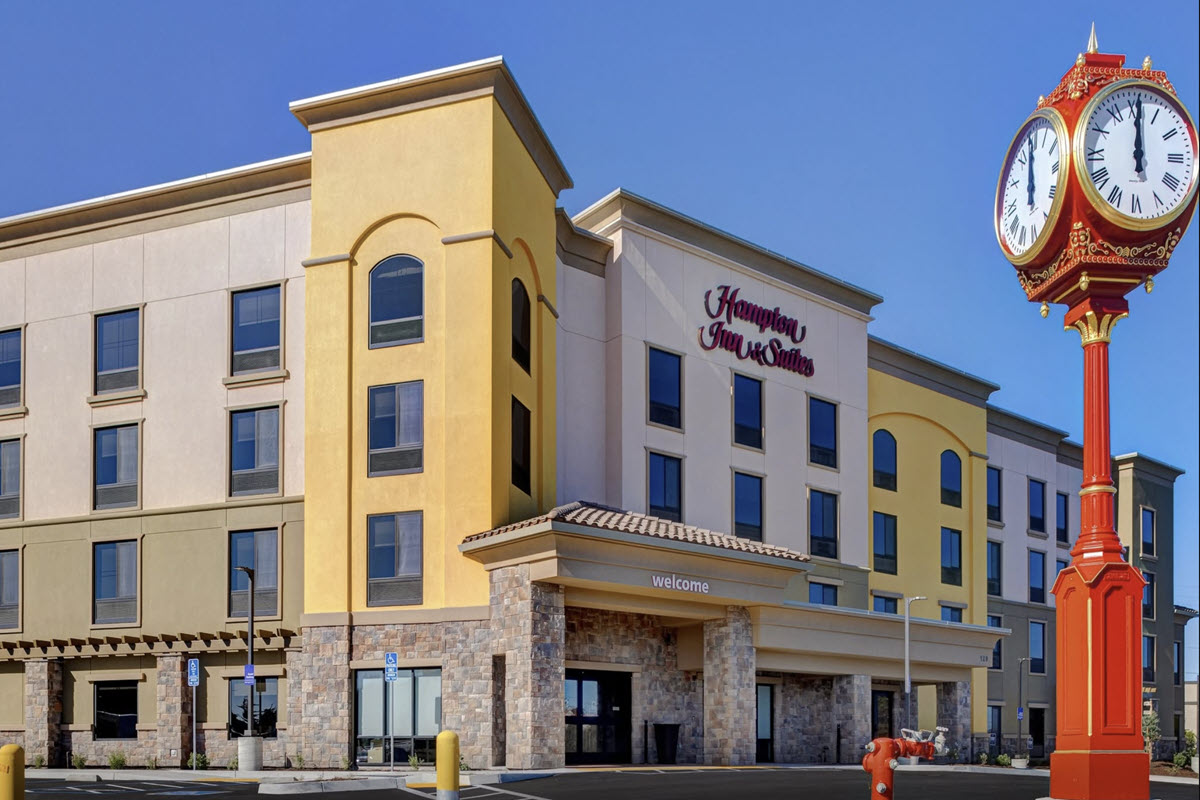
Hampton Inn appears in Marina's lodging inventory and City records refer to its construction near Reservation/Beach Road. In the official materials reviewed for this site, I did not locate a City economic-development subsidy agreement comparable to SpringHill Suites, Mercedes, Joby or the proposed luxury-hotel TOT sharing.
ROI/benefit logic: this is useful as a control case. A hotel can add rooms, jobs and TOT without a special tax-sharing agreement. If a later primary document establishes a Hampton-specific subsidy, this page should be updated rather than assuming none existed.
Monterey County Tourism Improvement District lodging list including Marina Hampton Inn ↗
Use case 4 - Mercedes-Benz: measurable sales-tax-sharing economics
The dealership agreement is the clearest use case for a measured in dollars City return. The project was described as a $40M+ project investment with more than 60,000 square feet of showroom/service facilities, more than 80 initial full-time-equivalent jobs and potential growth above 140 jobs over five years.
What Marina keeps during the seven-year sharing period
The agreement does not give the dealership all local sales tax. Marina shares 50% of the City’s 1% local sales-tax portion generated by the dealership. During the modeled seven years, the City still keeps the other half of that local 1% share. The City also receives other project-related local revenue identified in the staff analysis that is outside the shared sales-tax increment. After the sharing period or incentive cap is reached, Marina keeps 100% of its local sales-tax share.
City model: approximately $11.635 million in direct City tax revenue during the first seven years, compared with an incentive capped at up to $5 million. The projected gross difference is about $6.635 million before City service costs, discounting, or indirect effects. These are projections and depend on the dealership opening and meeting sales assumptions.
The City agreed to share 50% of its local 1% sales-tax share for a limited period to offset unusually high site-development and construction costs. Supplemental analysis examined extending the period to seven years to support an incentive cap of up to $5M. Under that model, the City estimated $11.635M in new direct tax money raised over seven years and about $3.195M in annual direct tax money raised after the sharing period.
ROI/benefit logic: comparing the modeled $11.635M direct City money raised with a maximum $5M incentive produces a simple gross benefit-to-incentive ratio of about 2.3:1 over seven years, before discounting, City service costs or indirect effects. That is not the same as a formal investment ROI, but it explains why staff concluded the temporary sharing could make economic sense.
Resolution 2025-49 and economic-development subsidy analysis ↗
Use case 5 - Joby Aviation: performance-based property-tax sharing
Joby began as an airport tenant and expanded into a major advanced-manufacturing use. In 2023, the City considered California's Capital Investment Incentive Program (CIIP) for a proposed major expansion. The staff report described a potential $700M real and business-personal-property investment and required at least $150M of eligible investment before incentive payments could begin.
Under the CIIP structure, Joby would receive 75% of specified incremental property-tax money raised above the base for 15 years, while the City retained 25% plus its base share. The 2023 model estimated about $6M in incentive payments to Joby and approximately $4M in City property-tax money raised over 15 years; after the incentive term the City receives its full share. The same analysis cited substantial job creation and about $300M/year in estimated local economic output.
ROI/benefit logic: the incentive is performance-based rather than an upfront check: no eligible investment, no incremental property tax to share. The City's return is the retained property-tax share, airport/lease activity, employment and secondary economic activity, followed by the full tax share after year 15.
2023 Joby CIIP analysis ↗ · 2019 Joby ground-lease announcement ↗
Use case 6 - New upper-upscale Dunes resort: higher subsidy, higher expected TOT
The current proposal would replace the previously approved 90-room Marriott Element, 110-room Marriott AC and 100-room Hyatt House plan with one 150-key upper-upscale resort: 125 conventional rooms plus 25 villas, along with restaurant/bar, spa, event space, pool and wellness amenities. CBRE concluded that the upper-upscale product was likely the stronger market strategy for the site.
Keyser Marston's preliminary work found the project feasible but indicated it may require about $25M of TOT money raised sharing, anticipated at 50:50. The July 2026 staff report listed estimated total TOT of $2.897M in 2030, $3.702M in 2031 and $3.986M in 2032. The development models and assistance terms were still being refined.
ROI/benefit logic: a 50:50 sharing structure means the City would receive substantial new TOT from the first day-to-day years while the developer receives assistance, then retain more after the assistance term. However, because the agreement and subsidy report are not final, this site labels the economics proposed rather than claiming a settled ROI.
July 1, 2026 luxury-hotel proposal, CBRE study and preliminary KMA feasibility ↗
Use case 7 - Sea Haven: housing, affordability and a park obligation that changed with inflation
Sea Haven - originally Marina Heights - is governed by a development agreement dating to 2004 for approximately 1,050 homes and related improvements. Later amendments addressed ownership changes, affordable housing, the 18-acre Sea Haven Park and changing project costs.
The park obligation illustrates why development agreements evolve. The park fee was increased from $1.5M to $2.1M for inflation; an additional $900,000 was structured to reach a $3M park budget. By 2023 the estimated park budget reached $3.6M; by 2025 City documents said the total park cost had risen to about $6.5M. The City ultimately moved toward constructing the park using impact fees already collected rather than continuing an increasingly complicated developer reimbursement mechanism.
ROI/benefit logic: the City's return is not a one-time check. It includes roughly 1,050 housing units, deed-restricted BMR opportunities, impact fees, property-tax growth, infrastructure and a major public park. The changing park arrangement also shows the risk of fixed developer obligations when construction costs rise faster than the original agreement.
2025 Sea Haven park / development-agreement amendment analysis ↗ · Sea Haven BMR program ↗
Use case 8 - Marina Station: growth finances its own infrastructure through a special tax district
Marina Station is a large mixed-use development planned for more than 1,300 homes, approximately 60,000 square feet of retail, 143,000 square feet of office and 650,000 square feet of flex/industrial space. In 2026 the City established a Community Facilities District (special tax district) and improvement area that can levy special taxes and issue bonds for specified public facilities, services and debt service.
The City also approved public-improvement agreements for development phases and off-site roadway work. This is materially different from asking the developer to pay the entire cost of an unrelated citywide facility: the special tax district and agreements are mechanisms to make the new development finance its legally supportable share of infrastructure and services.
ROI/benefit logic: public improvements are advanced as the development proceeds, while the City gains housing, commercial/industrial space, employment capacity, property and business tax base, parks/open space and completed infrastructure. No single cash “ROI percentage” is published because much of the return is infrastructure and future recurring money raised rather than an upfront City profit.
2025 Marina market study / Marina Station program ↗ · March 3, 2026 special tax district / special-tax proceedings ↗
What these use cases show
Marina has not used one standard incentive template. Some projects received no located special subsidy; some received fee deferrals; some use temporary sales-tax or TOT sharing; Joby's program shares only taxes created by new eligible investment; and large subdivisions use development agreements, impact fees and special tax districts. The common policy question is whether the incremental public benefit is likely to exceed the public concession and risk.
That context is relevant to evaluating claims about “developer giveaways,” but these examples should not be represented as funding for or endorsements of Measure Q.
Before connecting another City controversy to Measure Q
Marina has legitimate disputes about development agreements, parks, rentals, litigation, public records, old Council decisions and project delivery. A controversy does not automatically become a Measure Q funding fact.
| Test | Question to ask |
|---|---|
| Source | What primary record supports the claim, and what date or decision does it actually describe? |
| Context | Is a later outcome being compared with the facts, prices, contracts or law that existed when the decision was made? |
| Money | Is the amount unrestricted General Fund money that could actually be moved, or is it restricted, set aside, project-specific, future money raised or a negotiated obligation? |
| Magnitude | Even if the claim is correct, is the amount large enough to materially change the facilities funding problem? |
| Measure Q link | Does it change the tax, taxable base, facilities need, funding plan or available unrestricted resources? If not, keep it as a oversight issue rather than using it as a substitute for the Measure Q analysis. |
How do other City issues fit?
Parks, Preston Park, development incentives, litigation, recreation facilities and transportation projects can be legitimate questions without necessarily being the same financial question as Measure Q. Use the City Issues & Measure Q FAQ to see what is directly related, indirectly related, or financially separate.